Updated: October 21, 2026
You Stop Working Next Year. Here Is What to Check Before Your Last Day, and When.
Short answer
The year before you retire is about dates, not activities. Check your Social Security earnings record and write your full retirement age as a month. Ask your benefits office the company’s size and whether its drug coverage is creditable. Mark your 7-month Medicare window around your 65th birthday. If you are 65 or older on a job plan, mark the 8-month window that starts when the job or its coverage ends; COBRA does not extend it. Later, Form SSA-44 can lower a surcharge priced from your old salary. As of 2026.
Your checklist, with the date and the place to check
Here is the whole year on one page. Each row is a rule that applies to you on a set date, whether or not anyone reminds you. The dollar figures are for 2026 and change every January.
| What to check | When (as of 2026) | Where to check it |
|---|---|---|
| Your earnings record, and your full retirement age written as a month | About 12 months before your last day | Your my Social Security account at ssa.gov |
| Employer size (20 or more employees?) and whether the job plan pays first or second once you are 65 | Before you decide anything about Part B | Your benefits office, with the answer in writing |
| The notice that says whether your job drug coverage is creditable | Now, and each time a new one arrives | Your benefits office or plan administrator |
| Medicare Initial Enrollment Period, 7 months around your 65th birthday month | Opens 3 months before the month you turn 65, retired or not | Social Security handles the sign-up |
| Your Social Security application | Up to 4 months before the month you want benefits to start | ssa.gov or a Social Security office |
| Earnings test, if you claim before full retirement age and still earn wages | 2026 limits: $24,480, or $65,160 in the year you reach full retirement age | ssa.gov, Receiving Benefits While Working |
| 8-month Special Enrollment Period for Part B, if you are 65 or older on a current job plan | Starts when the job or its coverage ends, whichever is first. COBRA does not extend it | Social Security, in writing |
| Drug coverage gap | 63 days or more in a row without creditable coverage starts a lifelong penalty | medicare.gov, Part D late enrollment penalty |
| IRMAA, the surcharge priced from your tax return two years back | Your first Medicare years after the paycheck stops | Form SSA-44 at ssa.gov/medicare/lower-irmaa |
| Medicare Open Enrollment | October 15 to December 7, every year | The medicare.gov plan finder, or your SHIP |
Nothing here tells you when to claim or which plan to pick. Those answers depend on your health, your savings and your own record.
Twelve months out: which age is really yours?
Your full retirement age is set by your birth year, and for most women retiring now it is not 66. Social Security’s table puts everyone born in 1960 or later at 67. Births from 1955 through 1959 land on 66 plus 2, 4, 6, 8 or 10 months.
Two birthday rules shift the row. Born on January 1? Read the row for the year before. Born on the first of any month? Social Security figures your age as if you were born in the previous month.
Starting at 62 cuts your own benefit for good. For anyone born in 1960 or later, Social Security lists the reduction at 62 as 30 percent, approximate due to rounding.
Waiting past full retirement age adds 8 percent a year for anyone born in 1943 or later. The credits stop at 70. Log in to your account at ssa.gov, check that every working year shows real earnings, and copy your own benefit at full retirement age onto paper.
Delaying Social Security does not delay Medicare. The Medicare clock is built on your birthday.
Six to nine months out: two questions for your benefits office
Ask how many employees the company has, and whether the plan pays first or second once you are 65. That one number decides how safe it is to wait on Part B.
At 20 or more employees, the job plan pays first and Medicare second. Under 20, Medicare pays first. Medicare’s own warning is that job coverage might not pay for health services if you don’t have both Part A and Part B. You could be paying premiums and still be exposed.
Then ask for the creditable coverage notice for your drug coverage. It proves you owed no Part D penalty while you waited. Keep it for years.
The method: put four dates on one page
One sheet with four dates does most of the work. Write it before your last day, while HR still answers your emails.
- Your birthday window. The month you turn 65, the three months before it, and the three after. That is your Initial Enrollment Period.
- The first ending. Your last day of work and the last day of the job coverage. Circle whichever comes first. That is the one that starts the 8-month clock.
- The end of the 8 months. Count it from the circled date. Then ask Social Security to confirm the first and last month in writing.
- Where the letter lives. One line saying where the creditable coverage notice is filed.
A quick example. Your last day is June 30, and the plan covers you through July 31. The job ended first, so the window is tied to the June job end, not to the July 31 coverage end. Ask Social Security to confirm your first and last month in writing. If you then take 18 months of COBRA, the window has long closed by the time COBRA runs out.
The month you stop: what starts running
On your last day, two penalties start waiting for a missed date. The Part B penalty adds 10 percent to your premium for each full twelve-month period you could have had Part B and didn’t. You pay it for as long as you have Part B. Twenty-three months late counts as one full period, so 10 percent, not 20.
The standard Part B premium in 2026 is $202.90 a month (CMS, 2026 Medicare Parts A & B Premiums and Deductibles).
The drug penalty is 1 percent of a national base figure, $38.99 in 2026, for each full month without creditable coverage. It starts after a gap of 63 days in a row. You can owe it without ever having had a drug plan.
If a window does close, the General Enrollment Period runs January 1 to March 31 each year. Since 2023, coverage starts the month after you sign up. The old wait until July is gone.
Before anyone in your house claims: the spousal and survivor rules
A woman in her sixties may have a claim on up to four records: her own, her husband’s, a late husband’s and an ex-husband’s. Social Security pays the highest single amount you qualify for. It does not add them together.
- As a wife. Up to half of his full-retirement-age amount, from 62, after one continuous year of marriage, once he has filed. Born on January 2, 1954 or later? Filing for one benefit files for both, so the old switch strategy is closed.
- As an ex-wife. The marriage lasted ten years, the divorce is final, you are 62 and not married now. After two years divorced, he need not have filed, as long as he is 62 and fully insured.
- As a widow. From 60, starting at 71.5 percent of his benefit. The survivor age table runs two years behind: born in 1960, you read the 1958 row.
Two rules belong on the table when a husband plans his own claim. If he claims early, a widow’s benefit is capped at the larger of 82.5 percent of his primary insurance amount or the reduced amount he would have been receiving. If he delays past full retirement age, those credits carry into a widow’s benefit.
Those are facts about the rules, not advice on who should claim when. Bring marriage certificates and divorce decrees to Social Security, because these rules are decided on paper.
If you keep a part-time job after you start benefits
Before full retirement age, Social Security withholds $1 for every $2 you earn above $24,480 in 2026. In the year you reach full retirement age, the limit is $65,160 and the rate is $1 for every $3, counting only the months before the month you reach it.
Social Security says withheld benefits are not “lost.” At full retirement age your monthly benefit is raised to account for them. Only wages and net self-employment profit count. Pensions, annuities, interest and investment income do not.
Retiring mid-year has its own rule. In your first year, you count as retired in any month you earn $2,040 or less in 2026, or $5,430 if you reach full retirement age that year. Self-employed people face an hours test too.
The first year: a Medicare bill priced from your old salary
IRMAA is a surcharge on Part B and Part D, and it is set from your tax return two years back. For 2026, Social Security generally uses the return for tax year 2024. If you were still on a full salary then, your first retired year can be billed as if you still were.
In 2026 the surcharge starts above $109,000 on an individual return or $218,000 on a joint one. Above that line, Part B jumps from $202.90 to $284.10 a month. The brackets are cliffs, not slopes.
The fix is Form SSA-44. One of the qualifying life-changing events, in Social Security’s list, is that you or your spouse stopped working or reduced your hours. The surcharge is set automatically. The correction only happens if you send the form.
The Monday problem: the date nobody mails you
The last clock is not a federal one. The first Monday after work tends to feel fine. By the third, the week has lost its shape, because the job was quietly supplying six things at once.
Those six are a start time, an end time, a reason to leave the house, people you see without arranging it, a rhythm to the week, and an answer to “what did you do today?” Write down which ones you will lose. Then book one commitment with a fixed day for your first month, not five.
The National Institute on Aging gives the federal guideline as 150 minutes of moderate activity a week plus two days of muscle-strengthening, and it says household tasks can count toward the 150. If a flat mood lasts for months, tell your doctor.
A woman who reaches 65 can expect 20.7 more years on average; a man, 18.2 (NCHS, United States Life Tables, 2023, published 2025).
About 43 percent of women aged 75 and older live alone (U.S. Census Bureau, 2024, using 2022 survey data).
That is a planning horizon, not a forecast about you.
The book behind this checklist
 The Year You Retire on Amazon (opens in a new tab)
by Nancy Whitaker
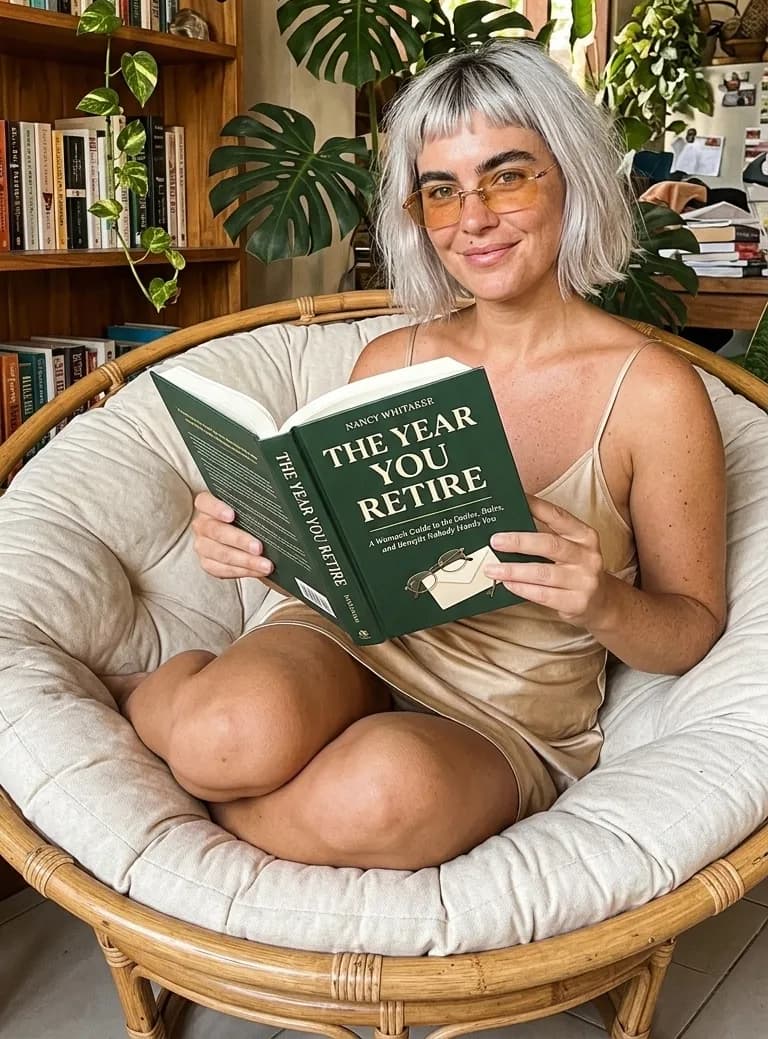
The Year You Retire by Nancy Whitaker is a 169-page guide to the dates and rules that start the day a woman stops working. It gathers them from six federal agencies, with a source and a date on every number.
The book adds the parks pass, tuition rules in eighteen states, the tax lines that change at 65, and fill-in pages for your first year.
- The Window That Closes: the 7-month and 8-month windows, the COBRA trap, the 20-employee question and both penalties
- The Age Ladder: the full retirement age table, the January 1 rule, early reductions and the retroactive lump-sum warning
- Her Own Record, and the Other Ones: wife, ex-wife and widow claims, the ten-year bridge rule, the survivor cap and remarriage
- What Changes Every January: every 2026 figure in one place, the IRMAA brackets, Form SSA-44 and where next year's numbers appear
- The Monday Problem: the six things a job supplied and the one-commitment rule for the first month
It fits if
- You retire this year and your job coverage ends with it
- You are a widow and were given a full retirement age from the wrong table
- Your Medicare premium is based on a salary you no longer earn
Skip it if
- You want investment or tax advice
- You live outside the US
- You want someone to tell you when to claim; this book only states the rules
Fair doubts
“Everything here is free on medicare.gov and ssa.gov.”
It is, and the book says so. The trouble is that it sits on dozens of pages and in Social Security’s staff manual. The survivor cap, for one, lives in that manual rather than on the pages written for widows.
“My HR office already walked me through it.”
HR knows your plan. It may not know your survivor age, your ex-husband’s record or the SSA-44. Use the checklist to ask better questions, and ask for each answer in writing.
Questions women ask the year before they retire
When should I sign up for Medicare if I retire after 65?
If you were covered by a group plan from your own or your husband's current job, you get an 8-month Special Enrollment Period. It starts when the job or that coverage ends, whichever comes first. COBRA and retiree coverage do not extend it. Ask Social Security to confirm your months in writing.
Does COBRA count as coverage for Medicare?
Not for holding your sign-up window open. As of 2026, Medicare says COBRA coverage does not extend your time to sign up, because it is not based on current employment. Retiree coverage works the same way.
Can I lower IRMAA after I retire?
You can ask. IRMAA is set from your tax return two years back. If your income fell because you or your spouse stopped working or cut hours, Form SSA-44 asks Social Security to use your newer income. See ssa.gov/medicare/lower-irmaa.
Will Social Security take back benefits if I keep working?
Before full retirement age, Social Security withholds part of your benefit once wages pass a yearly limit: $24,480 in 2026, or $65,160 in the year you reach full retirement age. Social Security says withheld benefits are not lost. At full retirement age your monthly benefit is raised to account for them.
What is the full retirement age for survivor benefits?
It is not always the same as for your own benefit. The survivor table runs two years behind the one for your own benefit. A widow born in 1960 has a full retirement age of 67 for her own benefit but reads the 1958 row, 66 and 8 months, for survivor benefits.
Rules on this page are as of 2026. Confirm your own dates with Social Security or 1-800-MEDICARE, or with your State Health Insurance Assistance Program (SHIP), which gives free counseling and is not connected to any insurance company.
Sources
- Medicare.gov, Working past 65 (8-month window, COBRA; checked October 21, 2026)
- Medicare.gov, Who pays first? (20-employee rule)
- CMS, 2026 Medicare Parts A & B Premiums and Deductibles (Part B premium and IRMAA brackets, 2026)
- Social Security, Receiving Benefits While Working (2026 earnings test)
- Social Security, Request to lower an IRMAA (Form SSA-44)
- NCHS, United States Life Tables, 2023 (published July 15, 2025)
- U.S. Census Bureau, Living Arrangements Varied Across Age Groups (May 30, 2024)
- The Year You Retire by Nancy Whitaker, chapters 1 to 6 and 13
